PNGX Equities • Fixed Income • Investor Education
Turnover eases to K2.37m
Just three counters, all steady
JMP Weekly Report | Week ending 6 November 2026
| TRADING VALUE K2.37m −56% on prior week |
TOTAL VOLUME 163,774 −68% on prior week |
STOCKS TRADED 3 of 11 BSP, KSL, CCP |
MARKET YIELD (LTM) 5.29% flat wow |
Weekly Trade Commentary
A thin, flat week — turnover eased to K2.37m on 163,774 shares as just three counters traded and none moved on price. BSP led on value (71,394 shares, K1.99m, steady at K27.95), KSL traded 71,774 shares steady at K3.90, and CCP 20,606 shares steady at K4.66. STO, NEM, KAM, NGP, CPL, SST and ADY did not trade — and PLC, also untraded, requested a trading halt during the week.
| Stock | Volume | Close (K) | Value (K) | Change | Change % |
|---|---|---|---|---|---|
| BSP | 71,394 | 27.95 | 1,994,928.62 | — | — |
| KSL | 71,774 | 3.90 | 279,918.60 | — | — |
| STO | — | 22.90 | — | — | — |
| NEM | — | 490.00 | — | — | — |
| KAM | — | 2.25 | — | — | — |
| NGP | — | 1.20 | — | — | — |
| CCP | 20,606 | 4.66 | 96,023.96 | — | — |
| CPL | — | 1.10 | — | — | — |
| PLC | — | 1.47 | — | — | — |
| SST | — | 50.00 | — | — | — |
| ADY | — | — | — | — | — |
| TOTAL | 163,774 | 2,370,871.18 | 0.00% |
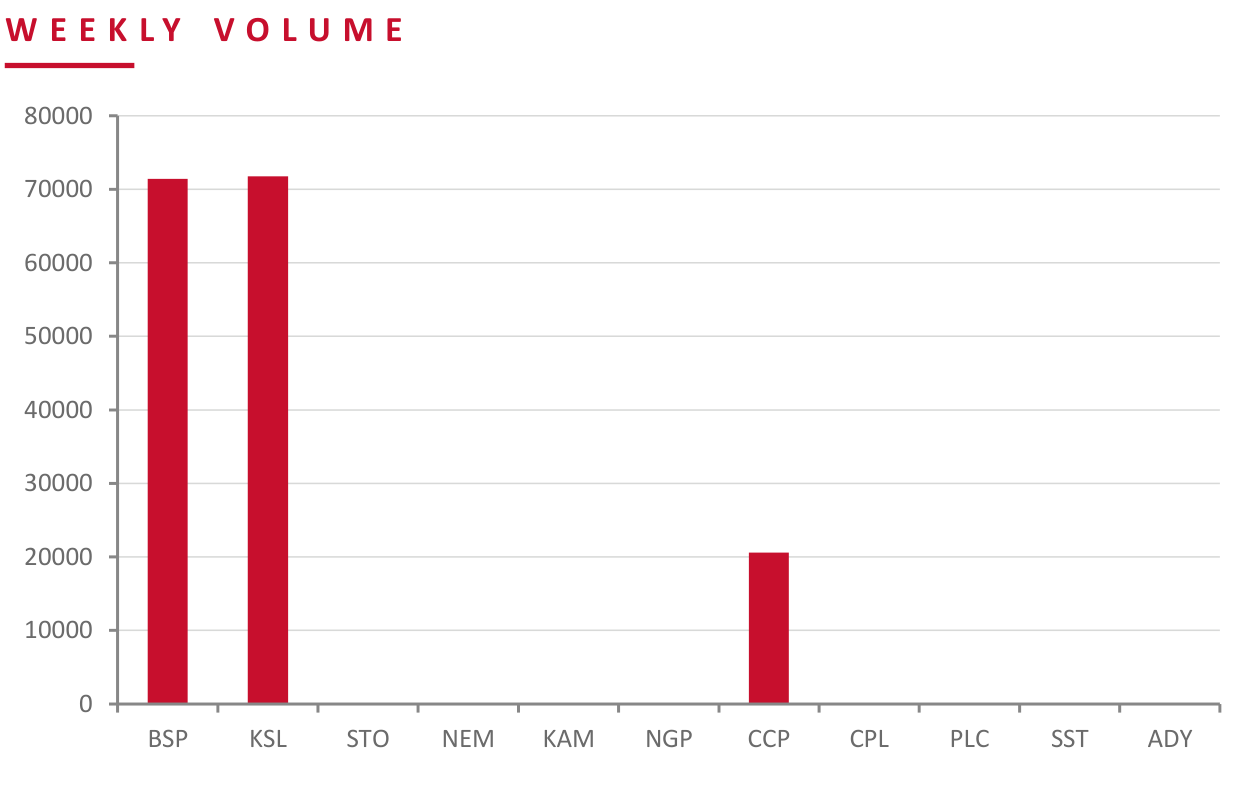 Source: PNGX matched on-market trades, week ending 6 November 2026. JMP Securities analysis.
Dividend Yield
Market-wide LTM dividend yield held at 5.29% this week (weighted by market cap, legacy methodology), unchanged across the board as the only names that traded — BSP, KSL and CCP — all closed steady. NGP (15.83%) still leads, then KAM (8.89%), KSL (8.59%) and BSP (6.87%). PLC remains pre- dividend; ADY has no dividend history yet.
| Stock | Issued Shares | Mkt Cap (K) | Int 24 | Fin 24 | Int 25 | Fin 25 | Yield % |
|---|---|---|---|---|---|---|---|
| BSP | 467,317,665 | 13,061,528,737 | 1.210 | 0.500 | 1.380 | 0.540 | 6.87% |
| KSL | 294,332,296 | 1,147,895,954 | 0.155 | 0.126 | 0.193 | 0.142 | 8.59% |
| STO | 3,261,616,703 | 74,691,022,499 | 0.414 | 0.559 | 0.443 | 0.514 | 4.18% |
| NEM* | 1,097,000,000 | 537,530,000,000 | — | 2.110 | 2.110 | USD $0.520 | 0.86% |
| KAM | 53,259,588 | 119,834,073 | — | 0.250 | — | 0.200 | 8.89% |
| NGP | 45,890,700 | 55,068,840 | 0.120 | 0.040 | 0.190 | — | 15.83% |
| CCP | 307,931,332 | 1,434,960,007 | 0.121 | 0.121 | 0.130 | 0.125 | 5.47% |
| CPL | 206,277,911 | 226,905,702 | — | 0.050* | 0.040 | 0.020 | 5.45% |
| PLC | 860,718,662 | 1,265,256,433 | — | — | — | — | — |
| SST | 31,008,237 | 1,550,411,850 | 0.300 | 0.400 | 0.650 | 0.350 | 2.00% |
| ADY | 316,766,640 | — | — | — | — | — | — |
| TOTAL / WEIGHTED-AVG | 5.29% | ||||||
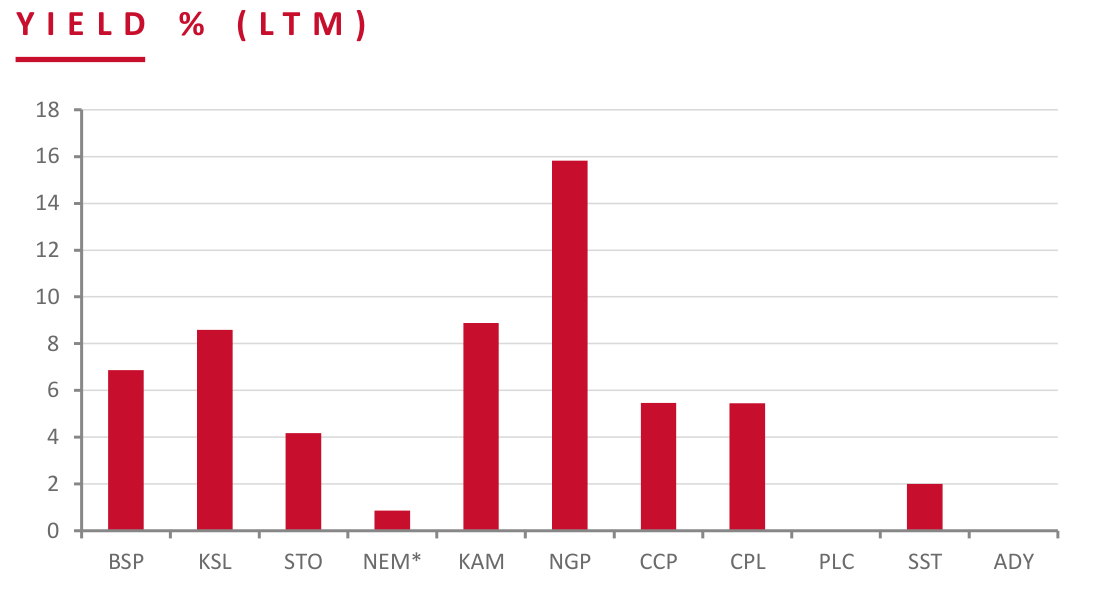

LTM = Last twelve months. Yields use most recently declared interim and final dividends. NEM dividends in USD until PGK rate announced; NEM excluded from market-wide yield. PLC now added.
Dividend Yield = Annual Dividends per Share ÷ Current Share Price × 100
Key Market Announcements
A lighter board, led by PLC. PLC requested a trading halt, lodged a master plan for a coastal estate at the Kido Rearea SEZ, and filed an application for quotation of securities. KAM gave notice of a substantial shareholding (Form 10B), and NEM lodged Form 4 and Form 144 filings for two directors.
| Stock | Announcement | Source |
|---|---|---|
| PLC | Request for trading halt; Kido Rearea SEZ coastal-estate master plan; quotation application | PNGX market announcements |
| KAM | Notice of substantial shareholding & Form 10B (Monica Salter) | PNGX market announcements |
| NEM | Form 4 and Form 144 filings (Viljoen, Toth) | PNGX market announcements |
Source: PNGX market announcements, 2–6 November 2026.
BPNG Treasury Bill Auction
Auction: 04-NOV-26 / GOI / Government Treasury Bill | Settlement: 06-NOV-26 | Amount on offer: K250.0m
| Terms | Issue / 63 | Issue / 91 | Issue / 182 | Issue / 273 | Issue / 364 | Total |
|---|---|---|---|---|---|---|
| Weighted Avg Yield | — | — | 4.66% | 5.04% | 5.07% | |
| Amount on Offer (K’m) | — | — | 20.00 | 50.00 | 180.00 | 250.00 |
| Bids Received (K’m) | — | — | 4.40 | 27.50 | 355.44 | 387.34 |
| Successful Bids (K’m) | — | — | 4.40 | 17.50 | 214.34 | 236.24 |
| Over / (Under) Subscribed (K’m) | — | — | −15.60 | −22.50 | +175.44 | +137.34 |
Source: Bank of Papua New Guinea — Domestic Markets Department, T-Bill auction 4 November 2026 (settlement 6 November 2026).
BPNG Government Bond Auction
NO NEW ISSUANCE — WEEK ENDING 6 NOVEMBER 2026
Auction: 27-OCT-26 / GOB / Government Bond | Settlement: 30-OCT-26 | Amount on offer: K300.0m
| Series | Offer | Bids | Successful | Yield | Weighted Avg | Coupon | Net Subscription |
|---|---|---|---|---|---|---|---|
| 2026/5057 — 3 yr | 60.00 | 97.58 | 77.58 | 6.18–6.23% | 6.20% | 6.20% | +37.58 |
| 2026/5058 — 5 yr | 60.00 | 102.89 | 78.89 | 6.55–6.63% | 6.59% | 6.60% | +42.89 |
| 2026/5059 — 7 yr | 60.00 | 64.28 | 44.28 | 6.69–6.73% | 6.71% | 6.70% | +4.28 |
| 2026/5060 — 10 yr | 60.00 | 66.60 | 66.60 | 6.70–6.83% | 6.81% | 6.80% | +6.60 |
| 2026/5061 — 15 yr | 60.00 | 60.00 | 35.00 | 7.20–7.23% | 7.22% | 7.20% | 0.00 |
| TOTAL | 300.00 | 391.35 | 302.35 | +91.35 |
Source: Bank of Papua New Guinea — Domestic Markets Department, GOB auction 27 October 2026 (settlement 30 October 2026).
Investor Education: Blue-Chip Stocks
What is a blue-chip stock?
A blue-chip stock is a share in a large, well-established company with a long history of stable earnings, sound finances and, usually, regular dividends. Blue chips are typically leaders in their industry and among the most widely held and actively traded shares on their exchange. The name comes from poker, where blue chips carry the highest value — first applied to top-priced Wall Street stocks in the 1920s. Defining features: large size and market value, a multi-decade track record through cycles, steady earnings, regular dividends, strong finances and sector leadership.
Globally the archetypes are names like Apple and Microsoft (US tech), Johnson & Johnson and Coca-Cola (US healthcare and staples), and on the ASX, BHP, Commonwealth Bank, CSL and Wesfarmers. On a smaller exchange like PNGX, ‘blue chip’ generally describes the largest, most liquid and most consistent dividend-paying counters — BSP Financial Group, Kina Securities and Credit Corporation are the usual reference points. (Examples are for education only, not recommendations.)
On the risk spectrum, blue chips sit at the low-risk, steadier-return end — opposite penny and small-caps, which offer higher growth potential but more volatility. Investors hold them for steadier prices through cycles, regular dividend income, high liquidity, and as a stable long-term core. But they aren’t risk-free: growth is slower than smaller companies, prices still fall in downturns, popular names can be expensive, and concentration in one sector or stock is a real risk. Many investors use blue chips as a portfolio foundation, balanced with other assets.
| 01 | Large & established High market value and a major listed company — decades of operating history through market cycles. |
| 02 | Steady earnings & dividends Consistent profits and revenue, with regular dividend payouts to shareholders. |
| 03 | Strong finances Manageable debt and solid capital — the balance-sheet strength to weather downturns. |
| 04 | Market leadership A top brand or the leading share in its sector, widely held and actively traded. |
What We’ve Been Reading
FEATURED READ
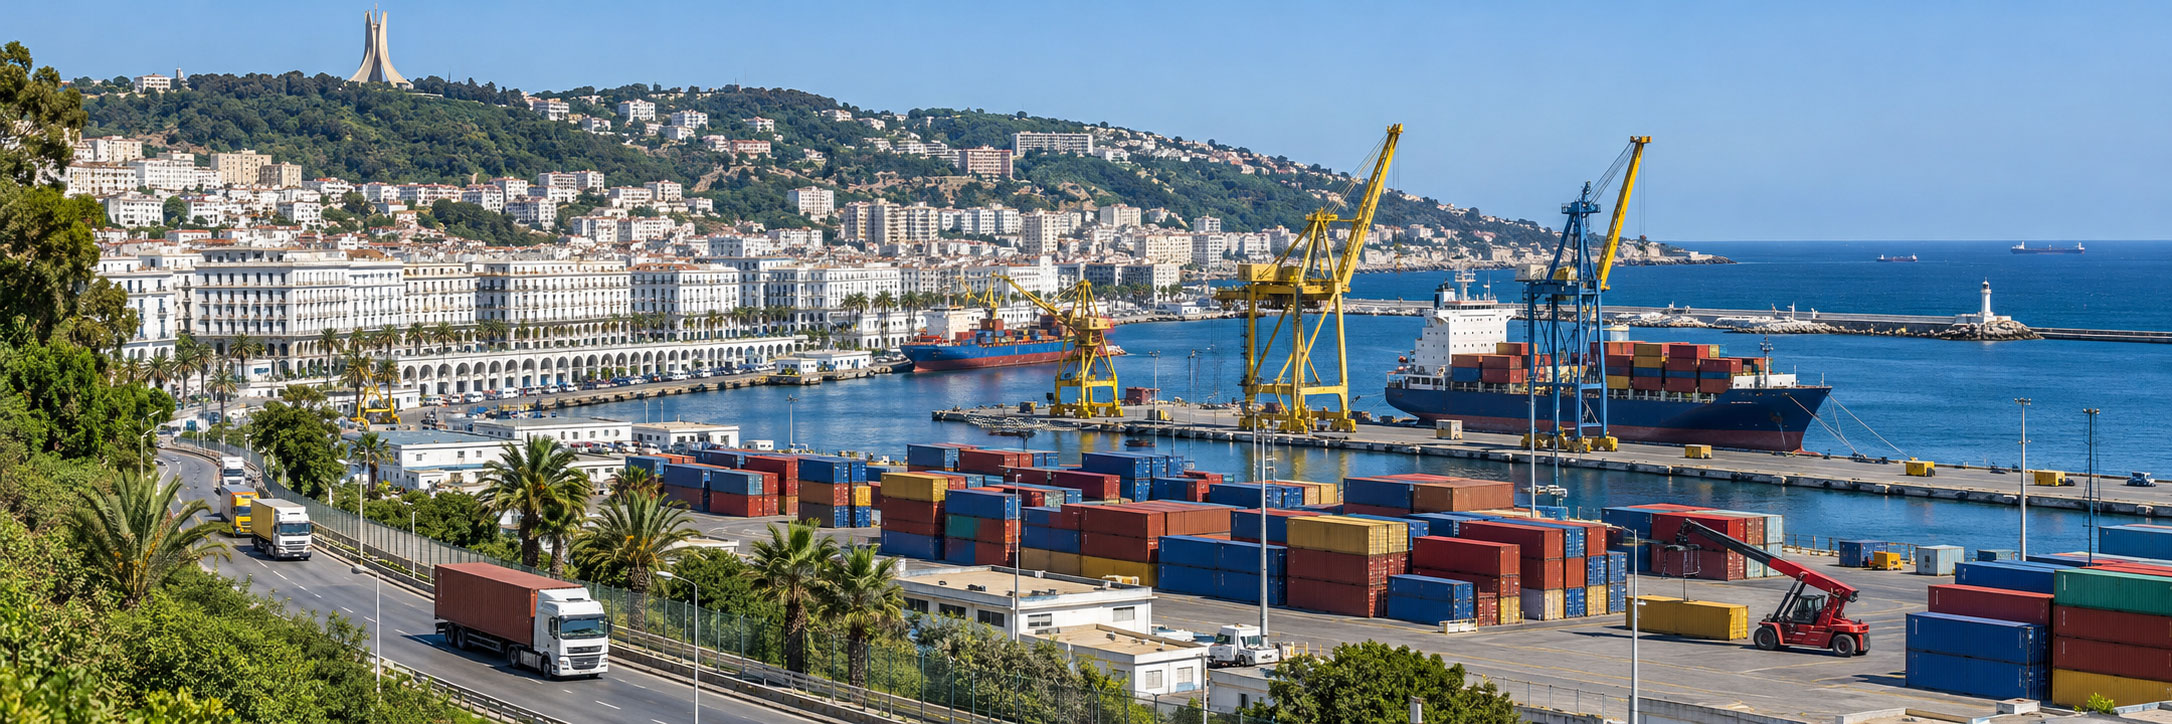
Algeria: creating conditions for lasting diversification
IMF Country Focus • Tsangarides, Painchaud & Salins
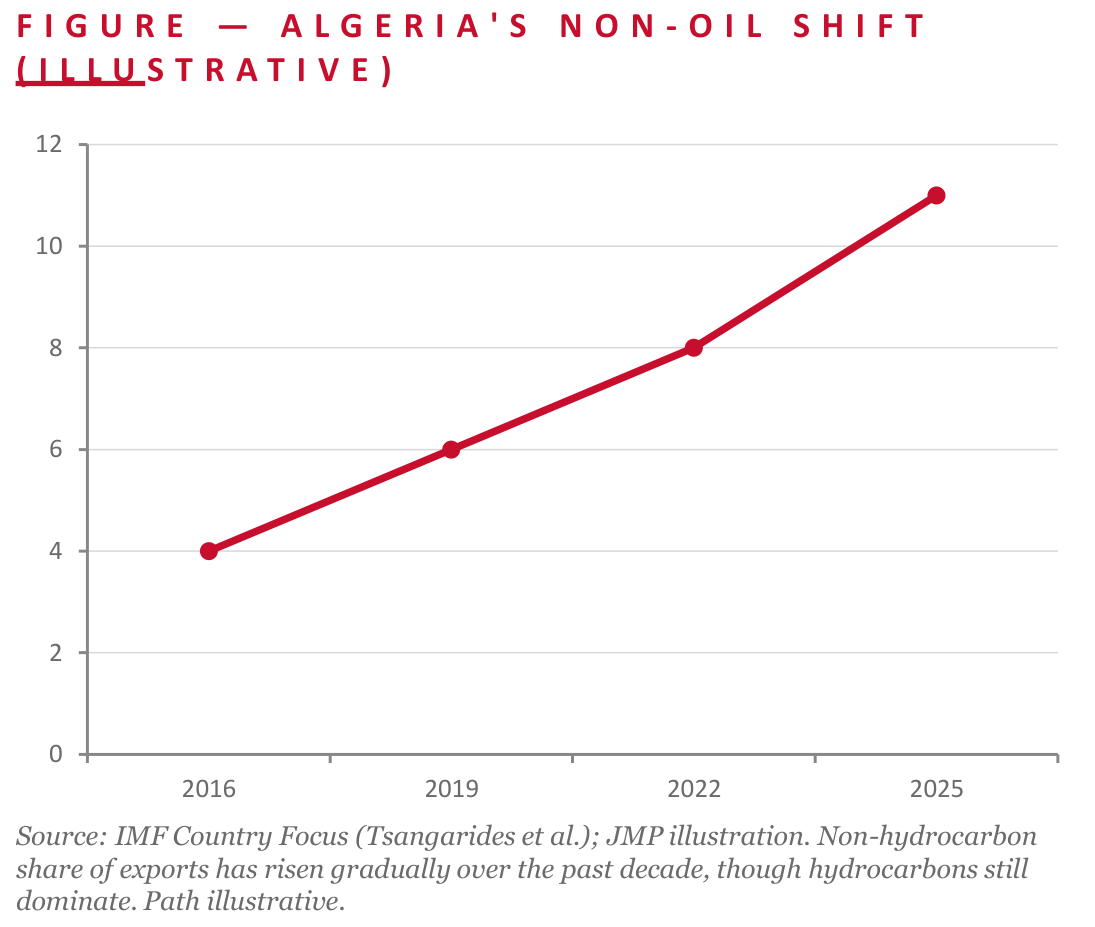
Algeria, one of Africa’s biggest energy exporters and closely tied to European markets, is making real but slow progress on diversifying beyond oil and gas. Hydrocarbons still supply most exports and much of public revenue, but the non-hydrocarbon shares of GDP and goods exports have risen gradually, and non-oil export revenues have grown over the past decade. The authorities’ strategy rests on large investment projects — mining, food and water security, transport and trade infrastructure — supported by streamlined procedures, governance reforms and a one-stop digital investment platform. The export base is broadening, but a handful of products still dominate the non-oil remainder.
The IMF’s caution is that the choice of projects matters as much as the amount spent. Large projects expand capacity and connectivity but require heavy financing, and recent investment has added to import demand and fiscal and external pressures. Directing money to the highest-impact projects — those that raise productivity, create jobs and build a dynamic private sector — would deliver more durable gains and keep priority spending affordable. Alongside, a more competitive private sector needs efficient infrastructure, access to finance and skills, predictable rules, and a level playing field between private firms and state-owned enterprises.
JMP read: Algeria is a mirror for PNG. Both are resource-dependent economies — hydrocarbons there, LNG and minerals here — trying to broaden their base while commodity revenues swing. The IMF’s prescription travels directly: pick investment projects for economic impact rather than headline size; rebuild fiscal and external buffers while commodity prices are favourable; and make the business environment competitive enough for a private sector to grow around the resource core — the diversification-and-buffers agenda that underpins the kina and PNG’s investment case.
Also on our desk
- Algeria is diversifying beyond oil and gas — but slowly; hydrocarbons still dominate exports — IMF
- The choice of investment projects matters as much as the amount spent — target the highest-impact ones — IMF
- Rebuilding fiscal and external buffers while prices are favourable is key to sustaining momentum — IMF
What this report covered this week
- Weekly trade activity — 3 stocks traded, K2.37m value (−56% pw); all steady
- Dividend yields — market-wide LTM 5.29% (unchanged across the board)
- PLC requests trading halt; Kido SEZ master plan; KAM & NEM filings
- BPNG T-Bill auction — over-subscribed by K137.34m
- BPNG bond auction — most recent (no new issuance this week)
- Investor Education — Blue-Chip Stocks
- External research — IMF on Algeria’s diversification
For Further Enquiries
Speak to your equities trader for any orders, research questions or market colour.
Benny Takin
Equities Trader — Primary contact, JMP Weekly Report
benny.takin@jmpmarkets.com
+675 7001 9121 / 320 0240
JMP Securities Limited
Level 3, ADF Haus, Musgrave Street
PO Box 2064, Port Moresby NCD, Papua New Guinea
Disclaimer
This report has been prepared by JMP Securities Limited (Capital Market Licence holder, Securities Commission of PNG). It is general information only and does not take into account the objectives, financial situation or needs of any particular person. It is not an offer or solicitation to buy or sell any security. Information is sourced from PNGX, Bank of Papua New Guinea and external publications cited herein, with JMP analysis. While reasonable care has been taken, no warranty is given as to accuracy or completeness; to the maximum extent permitted by law JMP accepts no liability for loss arising from reliance on this material. Investors should obtain independent professional advice before making any investment decision.JMP WEEKLY REPORT DTD 09.11.26