PNGX Equities • Fixed Income • Investor Education
KAM drives volume; turnover K3.03m
Five counters trade, value eases
JMP Weekly Report | Week ending 25 September 2026
| TRADING VALUE K3.03m −64% on prior week |
TOTAL VOLUME 1,224,157 +291% on prior week |
STOCKS TRADED 5 of 11 BSP, KSL, KAM, CCP, CPL |
MARKET YIELD (LTM) 5.28% flat wow |
Weekly Trade Commentary
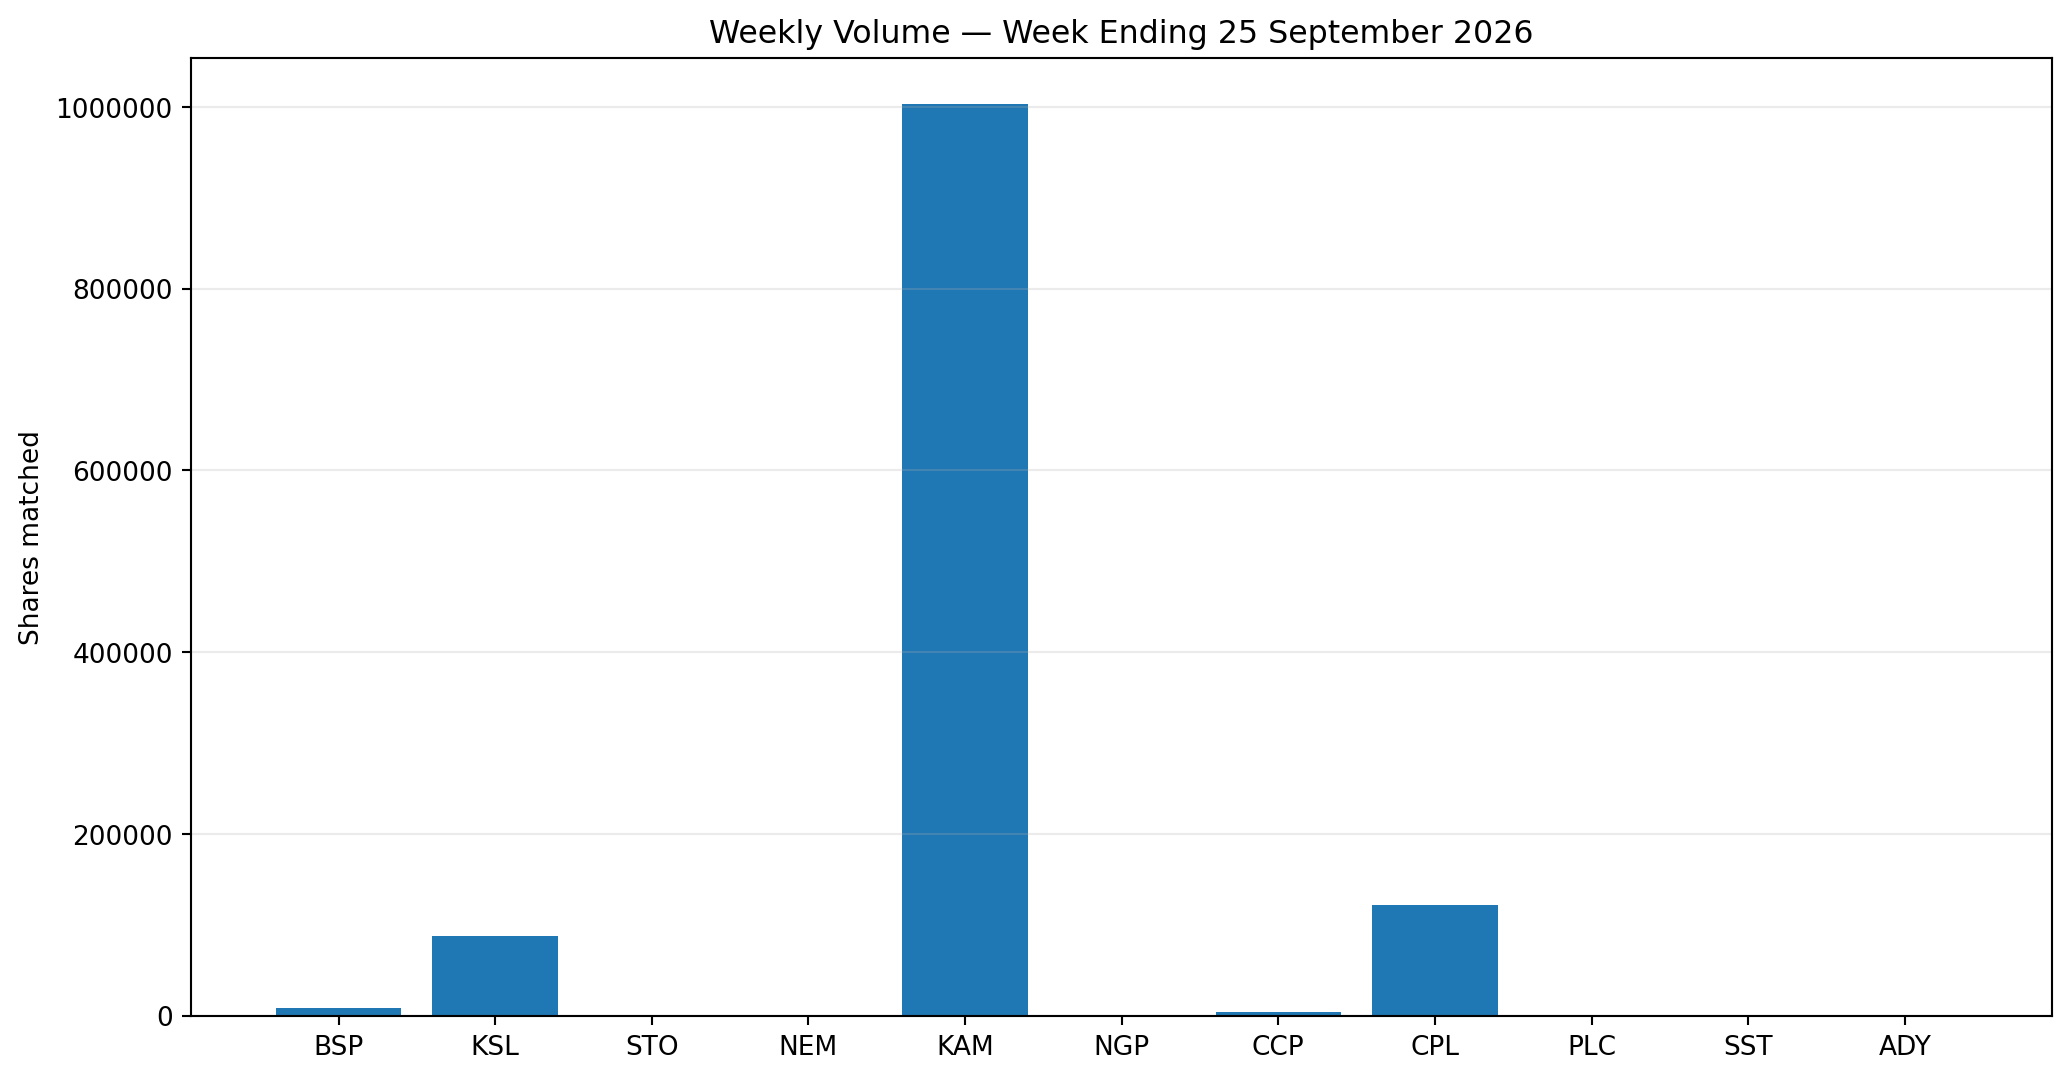
KAM drove the tape — turnover was K3.03m on 1.22m shares as five counters traded: volume jumped even as value eased. KAM alone traded 1,003,690 shares (steady at K2.25) for K2.26m — two-thirds of the week’s value. BSP was quiet (8,551 shares, steady at K27.95), KSL eased 11t to K4.30 on 87,153 shares, CPL traded 121,395 at K1.10 and CCP 3,368 at K4.66. Newly-listed ADY placed an opening bid of K1.25 but has yet to trade; STO, NEM, NGP, PLC and SST did not trade.
| Stock | Volume | Close (K) | Value (K) | Change | Change % |
|---|---|---|---|---|---|
| BSP | 8,551 | 27.95 | 239,000.45 | — | — |
| KSL | 87,153 | 4.30 | 380,939.66 | −0.11 | −2.49% |
| STO | — | 22.90 | — | — | — |
| NEM | — | 490.00 | — | — | — |
| KAM | 1,003,690 | 2.25 | 2,258,302.50 | — | — |
| NGP | — | 1.36 | — | — | — |
| CCP | 3,368 | 4.66 | 15,694.88 | — | — |
| CPL | 121,395 | 1.10 | 133,534.50 | — | — |
| PLC | — | 1.48 | — | — | — |
| SST | — | 50.00 | — | — | — |
| ADY | — | — | — | — | — |
| TOTAL | 1,224,157 | 3,027,471.99 | −0.03% |
Source: PNGX matched on-market trades, week ending 25 September 2026. JMP Securities analysis.
Dividend Yield
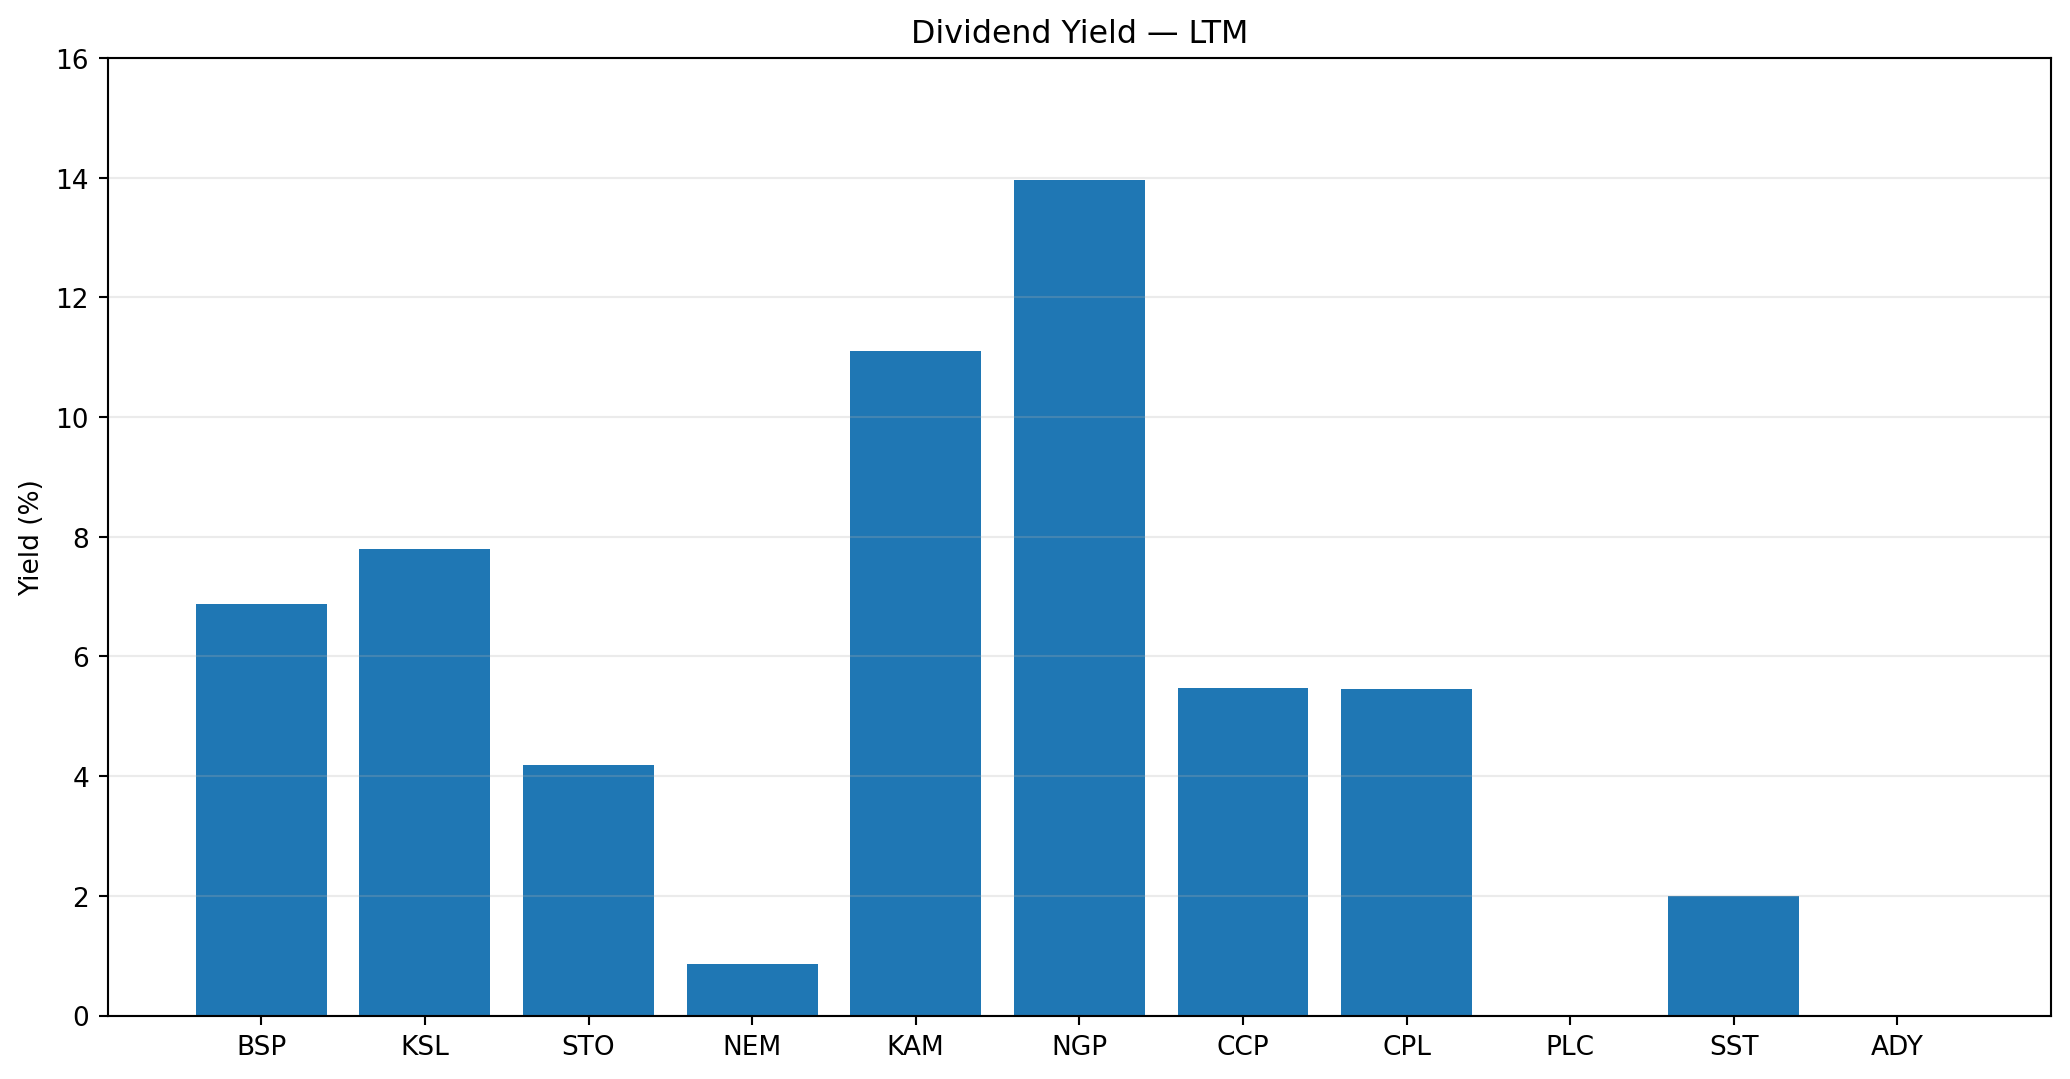
Market-wide LTM dividend yield held at 4.55% this week (weighted by market cap, legacy methodology). KSL firms to 7.79% on its slip to K4.30, while CPL eases to 5.45% as its price ticked up to K1.10; the rest of the board is unchanged. NGP (16.91%) still leads, then KAM (11.11%), KSL (7.79%) and BSP (6.87%). PLC remains pre-dividend; newly-listed ADY has no dividend history yet.
| Stock | Issued Shares | Mkt Cap (K) | Fin 24 | Int 25 | Fin 25 | Int 26 | Yield % |
|---|---|---|---|---|---|---|---|
| BSP | 467,317,665 | 13,061,528,737 | 1.210 | 0.500 | 1.380 | 0.540 | 6.87% |
| KSL | 294,332,296 | 1,265,628,873 | 0.155 | 0.126 | 0.193 | 0.142 | 7.79% |
| STO | 3,261,616,703 | 74,691,022,499 | 0.414 | 0.559 | 0.443 | 0.514 | 4.18% |
| NEM* | 1,097,000,000 | 537,530,000,000 | — | 2.110 | 2.110 | USD $0.520 | 0.86% |
| KAM | 53,259,588 | 119,834,073 | — | 0.250 | — | — | 11.11% |
| NGP | 45,890,700 | 62,411,352 | 0.120 | 0.040 | 0.190 | — | 13.97% |
| CCP | 307,931,332 | 1,434,960,007 | 0.121 | 0.121 | 0.130 | 0.125 | 5.47% |
| CPL | 206,277,911 | 226,905,702 | — | 0.050* | 0.040 | 0.020 | 5.45% |
| PLC | 860,718,662 | 1,273,863,620 | — | — | — | — | — |
| SST | 31,008,237 | 1,550,411,850 | 0.300 | 0.400 | 0.650 | 0.350 | 2.00% |
| ADY | 316,766,640 | — | — | — | — | — | — |
| TOTAL / WEIGHTED-AVG | 5.28% |
LTM = Last twelve months. Yields use most recently declared interim and final dividends. NEM dividends in USD until PGK rate announced; NEM excluded from market-wide yield. PLC & ADY now added.
*CPL Special Dividend 5t/share.
Dividend Yield = Annual Dividends per Share ÷ Current Share Price × 100
Key Market Announcements
A week of two coverage-universe changes. Adyton (ADY) listed on PNGX, lodging its listing documents and company disclosures — it placed an opening bid of K1.25 but is yet to trade — while PLC notified the market of a cessation of its securities. KAM published its final dividend announcement, and BSP updated its 2026 key financial dates.
| Stock | Announcement | Source |
|---|---|---|
| ADY | Listing documents & company disclosures (new PNGX listing — Adyton) | View announcement >> |
| PLC | Notification of cessation of securities | View announcement >> |
| KAM | Dividend announcement (final) | View announcement >> |
| BSP | Update to 2026 key financial dates | View announcement >> |
Source: PNGX market announcements, 21–25 September 2026.
BPNG Treasury Bill Auction
Auction: 23-SEP-26 / GOI / Government Treasury Bill | Settlement: 25-SEP-26 | Amount on offer: K270.0m
| Terms | Issue / 63 | Issue / 91 | Issue / 182 | Issue / 273 | Issue / 364 | Total |
|---|---|---|---|---|---|---|
| Weighted Avg Yield | — | — | 4.64% | 5.03% | 5.03% | |
| Amount on Offer (K’m) | — | — | 20.00 | 50.00 | 200.00 | 270.00 |
| Bids Received (K’m) | — | — | 2.40 | 53.00 | 236.92 | 292.32 |
| Successful Bids (K’m) | — | — | 2.40 | 53.00 | 214.60 | 270.00 |
| Over / (Under) Subscribed (K’m) | — | — | −17.60 | +3.00 | +36.92 | +22.32 |
Source: Bank of Papua New Guinea — Domestic Markets Department, T-Bill auction 23 September 2026 (settlement 25 September 2026).
BPNG Government Bond Auction
NEW ISSUANCE — WEEK ENDING 25 SEPTEMBER 2026
Auction: 22-SEP-26 / GOB / Government Bond | Settlement: 25-SEP-26 | Amount on offer: K300.0m
| Series | Offer | Bids | Successful | Yield | Weighted Avg | Coupon | Net Subscription |
|---|---|---|---|---|---|---|---|
| 2026/5057 — 3 yr | 50.00 | 60.00 | 55.00 | 6.17–6.20% | 6.18% | 6.20% | +10.00 |
| 2026/5058 — 5 yr | 50.00 | 66.10 | 66.10 | 6.50–6.60% | 6.57% | 6.57% | +16.10 |
| 2026/5059 — 7 yr | 50.00 | 112.20 | 112.20 | 6.60–6.70% | 6.68% | 6.70% | +62.20 |
| 2026/5060 — 10 yr | 100.00 | 126.54 | 110.54 | 6.70–6.80% | 6.77% | 6.80% | +26.54 |
| 2026/5061 — 15 yr | 50.00 | 56.00 | 50.00 | 7.17–7.20% | 7.18% | 7.20% | +6.00 |
| TOTAL | 300.00 | 420.00 | 393.00 | +120.84 |
Source: Bank of Papua New Guinea — Domestic Markets Department, GOB auction 22 September 2026 (settlement 25 September 2026).
Investor Education: Securities Lending
What is securities lending?
Securities lending is a temporary, collateralised transfer of securities in exchange for a fee. The owner (the lender) transfers shares or bonds to a borrower for a period; the borrower posts collateral worth more than the securities (typically 102–105%) and pays a fee. Legal title passes to the borrower, but the lender keeps the economic benefits — dividends are returned as “manufactured” payments — and the borrower must return equivalent securities on recall or at term. Think of it as a secured loan of stock, a close cousin of a repo.
Four groups make the market work: beneficial owners (long-term holders such as pension, super and sovereign funds) lend idle holdings for extra income; agent lenders (usually custodian banks) run the programme, find borrowers, manage collateral and often indemnify owners; borrowers (broker-dealers and investment banks) borrow to on-lend to hedge funds and market makers; and infrastructure providers (tri-party agents, CCPs and settlement systems) move and value securities and collateral daily. Borrowers need stock mainly for short-selling, settlement coverage and hedging.
Collateral does most of the risk work — backed by daily mark-to-market and margin calls — but not all of it: counterparty default, collateral shortfall, cash-reinvestment losses, operational slips (missed recalls or corporate actions), legal uncertainty on default, and loss of voting rights while title sits with the borrower. These are mitigated by over-collateralisation, credit limits, agent indemnities and industry master agreements (GMSLA). Securities lending is well established on the ASX; for PNGX, exchange and SCPNG requirements would need checking before any activity.
| 01 | Beneficial owners (lenders) Long-term holders — pension, super, insurers, mutual and sovereign funds — lend idle stock for incremental income. |
| 02 | Agent lenders Usually custodian banks: they run the programme, find borrowers, manage collateral and often indemnify owners against default. |
| 03 | Borrowers Broker-dealers and investment banks, typically borrowing to on-lend to hedge funds and market makers via prime brokerage. |
| 04 | Infrastructure providers Tri-party collateral agents, central counterparties and settlement systems that move and value securities and collateral daily. |
What We’ve Been Reading
FEATURED READ
Global growth over home bias
Monthly Bell (Bell Potter) • Rob Crookston, Strategist
Bell Potter’s positioning rests on one judgement: more exposure to global equities, less to domestic. It is overweight global shares because earnings — not sentiment — are carrying markets higher, driven by a sustained lift in corporate capital spending on compute and data infrastructure, most visible in the US and now broadening beyond mega-cap tech to businesses and governments. Valuations look reasonable once earnings growth is taken into account, and profit upgrades have been broad-based. Emerging markets offer similar upside more cheaply, though Bell Potter has trimmed slightly given how concentrated recent gains are in a few memory-chip and semiconductor names.
It is underweight Australia for the opposite reason: home inflation has proved stickier than offshore, and Bell Potter thinks the RBA still has work to do — more likely to hike than hold in the next three months — with higher-for-longer rates and the recent Budget weighing on housing and consumption. Australian profit forecasts were revised down through reporting season, with strength narrow and largely in resources (copper and AI-infrastructure commodities). Bonds and cash are held for defence, not offence: underweight duration, but retaining government bonds as insurance and favouring higher-quality credit over reaching for yield.
JMP read: The relevant thread for PNG is the resources call. Bell Potter’s overweight to the global AI-infrastructure build — and the copper and commodity demand it drives — is supportive for PNG’s export complex, even as it steers away from domestic-cycle markets like Australia’s. The three risks it flags — an AI-capex disappointment, stickier inflation forcing more hikes, and a Middle East oil shock — are the same forces that set the backdrop for the kina and PNGX.
Figure — AI-Capex Cycle (Illustrative)
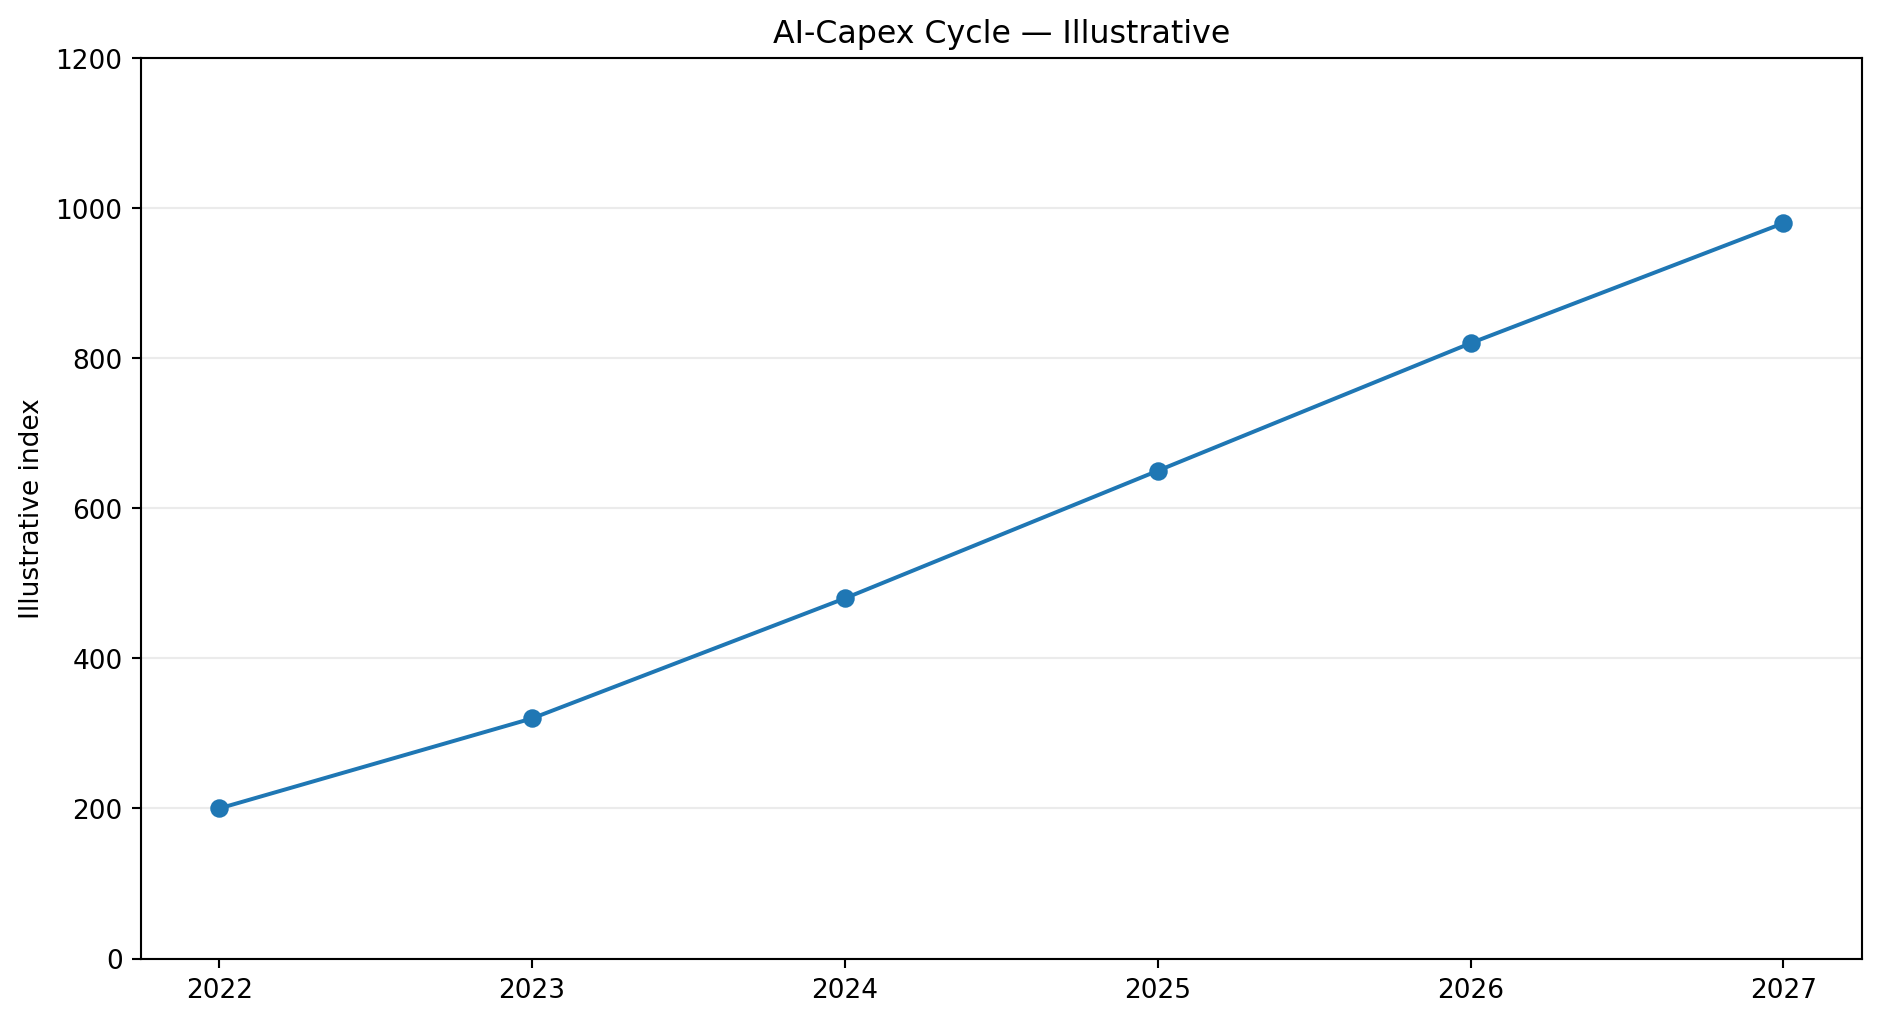
Source: Bell Potter (Monthly Bell, September); JMP illustration. Sustained corporate spending on compute and data infrastructure underpins the global-equities overweight. Illustrative path.
Also on our desk
- Overweight global equities — earnings, led by broadening AI-infrastructure capex, are carrying markets — Bell Potter
- Underweight Australia — stickier inflation; the RBA looks likelier to hike than hold near-term — Bell Potter
- Bonds and cash for defence not offence; key risks are AI capex, inflation and oil — Bell Potter
What this report covered this week
- Weekly trade activity — 5 stocks traded, K3.03m value (−64% pw); KAM drove volume
- Dividend yields — market-wide LTM 5.28% (flat; KSL 7.79%, CPL 5.45%)
- ADY lists on PNGX; PLC cessation of securities; KAM dividend; BSP dates
- BPNG T-Bill auction — over-subscribed by K22.32m
- BPNG bond auction — new K300m issuance, net subscription K120.84m
- Investor Education — Securities Lending
- External research — Bell Potter: global growth over home bias
For Further Enquiries
Speak to your equities trader for any orders, research questions or market colour.
Benny Takin
Equities Trader — Primary contact, JMP Weekly Report
benny.takin@jmpmarkets.com
+675 7001 9121 / 320 0240
JMP Securities Limited
Level 3, ADF Haus, Musgrave Street
PO Box 2064, Port Moresby NCD, Papua New Guinea
Disclaimer
This report has been prepared by JMP Securities Limited (Capital Market Licence holder, Securities Commission of PNG). It is general information only and does not take into account the objectives, financial situation or needs of any particular person. It is not an offer or solicitation to buy or sell any security. Information is sourced from PNGX, Bank of Papua New Guinea and external publications cited herein, with JMP analysis. While reasonable care has been taken, no warranty is given as to accuracy or completeness; to the maximum extent permitted by law JMP accepts no liability for loss arising from reliance on this material. Investors should obtain independent professional advice before making any investment decision.