PNGX Equities • Fixed Income • Investor Education
Activity rebounds: turnover K4.79m
PLC and BSP drive the tape
JMP Weekly Report | Week ending 9 October 2026
| TRADING VALUE K4.79m ×28 on prior week |
TOTAL VOLUME 1,509,010 ×49 on prior week |
STOCKS TRADED 4 of 11 BSP, KSL, CPL, PLC |
MARKET YIELD (LTM) 5.28% flat wow |
Weekly Trade Commentary
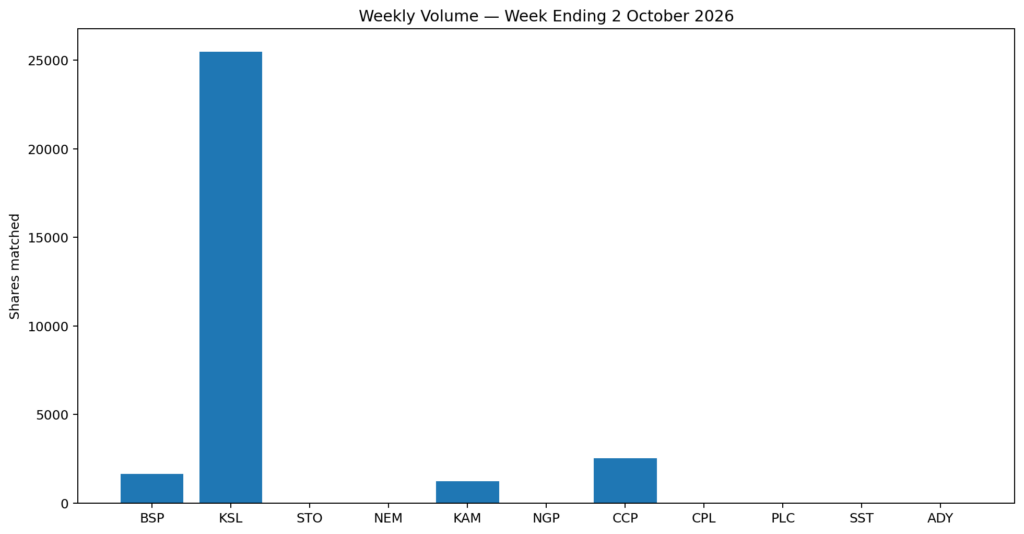
Activity rebounded sharply off the dormant prior week — turnover jumped to K4.79m on 1.51m shares, though still only four counters traded. PLC drove the volume with a 1.36m-share block, steady at K1.48 for K2.00m, while BSP led on value at K2.60m (92,881 shares, steady at K27.95). KSL eased a further 7t to K4.03 on 44,792 shares, and CPL added 11,412 shares at K1.10. STO, NEM, KAM, NGP, CCP, SST and newly-listed ADY did not trade.
| Stock | Volume | Close (K) | Value (K) | Change | Change % |
|---|---|---|---|---|---|
| BSP | 92,881 | 27.95 | 2,596,023.95 | — | — |
| KSL | 44,792 | 4.03 | 180,511.76 | −0.07 | −1.71% |
| STO | — | 22.90 | — | — | — |
| NEM | — | 490.00 | — | — | — |
| KAM | — | 2.25 | — | — | — |
| NGP | — | 1.36 | — | — | — |
| CCP | — | 4.66 | — | — | — |
| CPL | 11,412 | 1.10 | 12,553.20 | — | — |
| PLC | 1,359,925 | 1.48 | 2,000,028.24 | — | — |
| SST | — | 50.00 | — | — | — |
| ADY | — | — | — | — | — |
| TOTAL | 1,509,010 | 4,789,117.15 | −0.02% |
Source: PNGX matched on-market trades, week ending 9 October 2026. JMP Securities analysis.
Dividend Yield
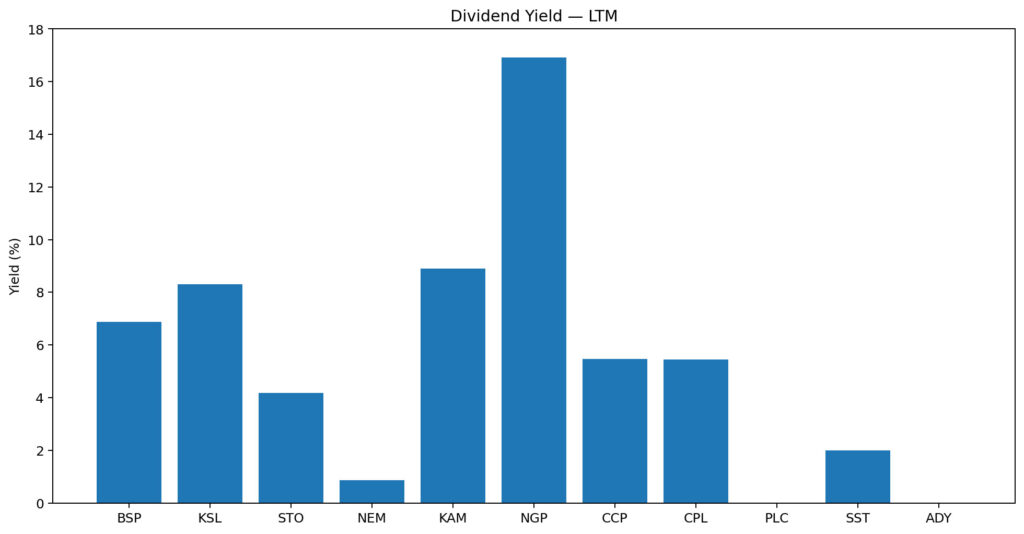
Market-wide LTM dividend yield held at 4.55% this week (weighted by market cap, legacy methodology). KSL firms further to 8.31% on its slip to K4.03, while KAM eases to 8.89% after declaring a 2026 interim of K0.200 (replacing last year’s K0.250 in the LTM window); the rest of the board is unchanged. NGP (16.91%) still leads, then KAM (8.89%), KSL (8.31%) and BSP (6.87%). PLC remains pre-dividend; ADY has no dividend history yet.
| Stock | Issued Shares | Mkt Cap (K) | Fin 24 | Int 25 | Fin 25 | Int 26 | Yield % |
|---|---|---|---|---|---|---|---|
| BSP | 467,317,665 | 13,061,528,737 | 1.210 | 0.500 | 1.380 | 0.540 | 6.87% |
| KSL | 294,332,296 | 1,186,159,153 | 0.155 | 0.126 | 0.193 | 0.142 | 8.31% |
| STO | 3,261,616,703 | 74,691,022,499 | 0.414 | 0.559 | 0.443 | 0.514 | 4.18% |
| NEM* | 1,097,000,000 | 537,530,000,000 | — | 2.110 | 2.110 | USD $0.520 | 0.86% |
| KAM | 53,259,588 | 119,834,073 | — | 0.250 | — | 0.200 | 8.89% |
| NGP | 45,890,700 | 62,411,352 | 0.120 | 0.040 | 0.190 | — | 16.91% |
| CCP | 307,931,332 | 1,434,960,007 | 0.121 | 0.121 | 0.130 | 0.125 | 5.47% |
| CPL | 206,277,911 | 226,905,702 | — | 0.050* | 0.040 | 0.020 | 5.45% |
| PLC | 860,718,662 | 1,273,863,620 | — | — | — | — | — |
| SST | 31,008,237 | 1,550,411,850 | 0.300 | 0.400 | 0.650 | 0.350 | 2.00% |
| ADY | 316,766,640 | — | — | — | — | — | — |
| TOTAL / WEIGHTED-AVG | 5.28% |
LTM = Last twelve months. Yields use most recently declared interim and final dividends. NEM dividends in USD until PGK rate announced; NEM excluded from market-wide yield. PLC now added.
Dividend Yield = Annual Dividends per Share ÷ Current Share Price × 100
Key Market Announcements
A light announcements week. KSL filed an Appendix 2B and an Appendix 10B (change in directors’/CEO’s interests); KAM published its NTA as at 30 September; and NEM lodged two directors’ Form 4 filings. Off the coverage list, CGA appointed a new company secretary.
| Stock | Announcement | Source |
|---|---|---|
| KSL | Appendix 2B; Appendix 10B — change in directors’ / CEO’s interests | View announcement >> |
| KAM | NTA as at 30 September 2026 | View announcement >> |
| NEM | Form 4 filings (Toth, Viljoen) | View announcement >> |
| CGA | Appointment of new company secretary (off-coverage) | View announcement >> |
Source: PNGX market announcements, 5–9 October 2026.
BPNG Treasury Bill Auction
Auction: 07-OCT-26 / GOI / Government Treasury Bill | Settlement: 09-OCT-26 | Amount on offer: K240.0m
| Terms | Issue / 63 | Issue / 91 | Issue / 182 | Issue / 273 | Issue / 364 | Total |
|---|---|---|---|---|---|---|
| Weighted Avg Yield | — | — | 4.65% | 5.04% | 5.05% | |
| Amount on Offer (K’m) | — | — | 30.00 | 60.00 | 150.00 | 240.00 |
| Bids Received (K’m) | — | — | 16.63 | 31.00 | 280.40 | 328.03 |
| Successful Bids (K’m) | — | — | 16.63 | 31.00 | 280.40 | 328.03 |
| Over / (Under) Subscribed (K’m) | — | — | −13.37 | −29.00 | +130.40 | +88.03 |
Source: Bank of Papua New Guinea — Domestic Markets Department, T-Bill auction 7 October 2026 (settlement 9 October 2026).
BPNG Government Bond Auction
NO NEW ISSUANCE — WEEK ENDING 9 OCTOBER 2026
Auction: 22-SEP-26 / GOB / Government Bond | Settlement: 25-SEP-26 | Amount on offer: K300.0m
| Series | Offer | Bids | Successful | Yield | Weighted Avg | Coupon | Net Subscription |
|---|---|---|---|---|---|---|---|
| 2026/5057 — 3 yr | 50.00 | 60.00 | 55.00 | 6.17–6.20% | 6.18% | 6.20% | +10.00 |
| 2026/5058 — 5 yr | 50.00 | 66.10 | 66.10 | 6.50–6.60% | 6.57% | 6.57% | +16.10 |
| 2026/5059 — 7 yr | 50.00 | 112.20 | 112.20 | 6.60–6.70% | 6.68% | 6.70% | +62.20 |
| 2026/5060 — 10 yr | 100.00 | 126.54 | 110.54 | 6.70–6.80% | 6.77% | 6.80% | +26.54 |
| 2026/5061 — 15 yr | 50.00 | 56.00 | 50.00 | 7.17–7.20% | 7.18% | 7.20% | +6.00 |
| TOTAL | 300.00 | 420.00 | 393.00 | +120.84 |
Source: Bank of Papua New Guinea — Domestic Markets Department, GOB auction 22 September 2026 (settlement 25 September 2026).
Investor Education: Behavioural Finance
What is behavioural finance?
Behavioural finance combines psychology and economics to explain how real people make financial decisions — and how their predictable mistakes can push prices away from fundamental value. Traditional finance assumes investors are fully rational, weigh information correctly and arbitrage away any mispricing. Behavioural finance observes the opposite: investors use mental shortcuts and are swayed by emotion, their errors are systematic rather than random, and because arbitrage is risky and costly, mispricing can persist for long periods.
Biases fall into two families. Cognitive errors are faulty reasoning — anchoring on an initial number like the buy price, availability, representativeness, confirmation bias, mental accounting and framing — and are often correctable with better data and process. Emotional biases are driven by feeling — loss aversion, overconfidence, herding, regret aversion, status-quo bias and the endowment effect — and are harder to fix, so are better managed with rules than with information.
Because biases are systematic, they move prices, not just individual portfolios — showing up as momentum, long-run reversal, post-earnings drift and bubbles, which persist where arbitrage is limited by fundamental and noise-trader risk, costs, and thin, hard-to-borrow markets. The practical defence is process over willpower: a written checklist and price target, pre-committed exit and review rules, portfolio-level thinking, actively arguing the other side, a trade journal, and scheduled rebalancing.
| 01 | Anchoring Fixing on an initial number — the last traded price or your buy price — and adjusting away from it too little. |
| 02 | Confirmation bias Seeking information that supports your view and discounting whatever contradicts it. |
| 03 | Loss aversion Feeling the pain of a loss more than the pleasure of a gain — so losers are held too long. |
| 04 | Herding Following the crowd rather than your own analysis, amplifying momentum and bubbles. |
What We’ve Been Reading
FEATURED READ
Rising sovereign yields raise the fiscal stakes
IMF Blog • Dabla-Norris & Valdés
High and rising public debt is intensifying the feedback between fiscal policy and interest rates. New IMF research finds that when debt is already high, rising policy rates lead to a larger deterioration in deficits and debt, and market rates become more sensitive to fiscal news. Long-term sovereign yields have jumped: between February and September the G7’s average 10-year yield rose over 1 percentage point to its highest in nearly two decades, even as global public debt is set to exceed 100% of GDP by 2030 — a level last seen just after World War II. Oil prices, sticky inflation, stronger investment demand and AI-linked growth all play a part, but fiscal fundamentals are central.
The budgetary squeeze is already visible. The effective average interest cost of government financing is projected to climb from 2.3% in 2021 to 3.7% by 2031; in the US, interest payments rise from about 2.8% of GDP pre-pandemic to 5.7% by 2031 — roughly the Social Security bill — while low-income countries already spend over 15% of tax revenue on interest. With new-debt rates now exceeding nominal growth in more economies, governments need stronger primary balances just to stabilise debt.
JMP read: For PNG the message is twofold. First, the global rate backdrop — a G7 10-year at two-decade highs — raises the cost and tightens the availability of external finance, and the IMF warns the favourable window for emerging and frontier issuers may not last if risk appetite shifts. Second, the prescription lands at home: for lower-income economies the priority is stronger tax systems and spending efficiency to keep debt sustainable — the fiscal discipline that underpins the kina and domestic yields.
Figure — Rising Interest Costs
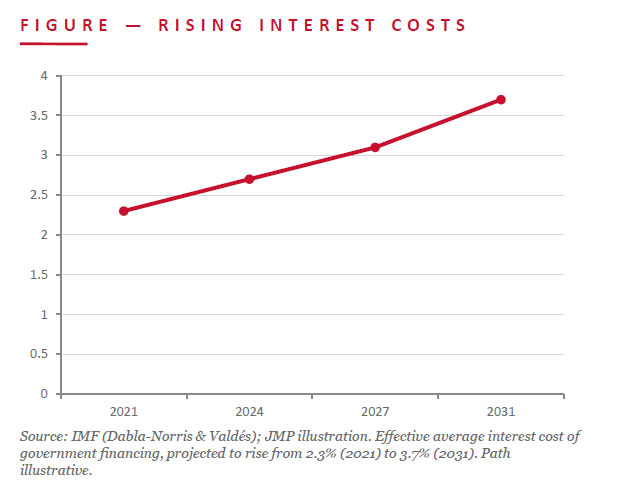
Source: IMF (Dabla-Norris & Valdés); JMP illustration. Effective average interest cost of government financing, projected to rise from 2.3% (2021) to 3.7% (2031). Path illustrative.
Also on our desk
- The G7’s average 10-year yield rose over 1pp between February and September — a near two-decade high — IMF
- Global public debt is set to exceed 100% of GDP by 2030 — last seen just after WWII — IMF
- Average government interest cost is projected to climb from 2.3% (2021) to 3.7% (2031) — IMF
What this report covered this week
- Weekly trade activity — 4 stocks traded, K4.79m value (×28 pw); PLC & BSP lead
- Dividend yields — market-wide LTM 5.28% (flat; KSL 8.31%, KAM 8.89% on new interim)
- KSL Appendix 2B/10B; KAM NTA; NEM Form 4 filings; CGA company secretary
- BPNG T-Bill auction — over-subscribed by K88.03m (offer cut to K240m)
- BPNG bond auction — most recent (no new issuance this week)
- Investor Education — Behavioural Finance
- External research — IMF on rising sovereign yields & fiscal stakes
For Further Enquiries
Speak to your equities trader for any orders, research questions or market colour.
Benny Takin
Equities Trader — Primary contact, JMP Weekly Report
benny.takin@jmpmarkets.com
+675 7001 9121 / 320 0240
JMP Securities Limited
Level 3, ADF Haus, Musgrave Street
PO Box 2064, Port Moresby NCD, Papua New Guinea
Disclaimer
This report has been prepared by JMP Securities Limited (Capital Market Licence holder, Securities Commission of PNG). It is general information only and does not take into account the objectives, financial situation or needs of any particular person. It is not an offer or solicitation to buy or sell any security. Information is sourced from PNGX, Bank of Papua New Guinea and external publications cited herein, with JMP analysis. While reasonable care has been taken, no warranty is given as to accuracy or completeness; to the maximum extent permitted by law JMP accepts no liability for loss arising from reliance on this material. Investors should obtain independent professional advice before making any investment decision.